
Story
AbCellera and Recursion Valuations Diverge Sharply Amid Contrasting Financials
Summary
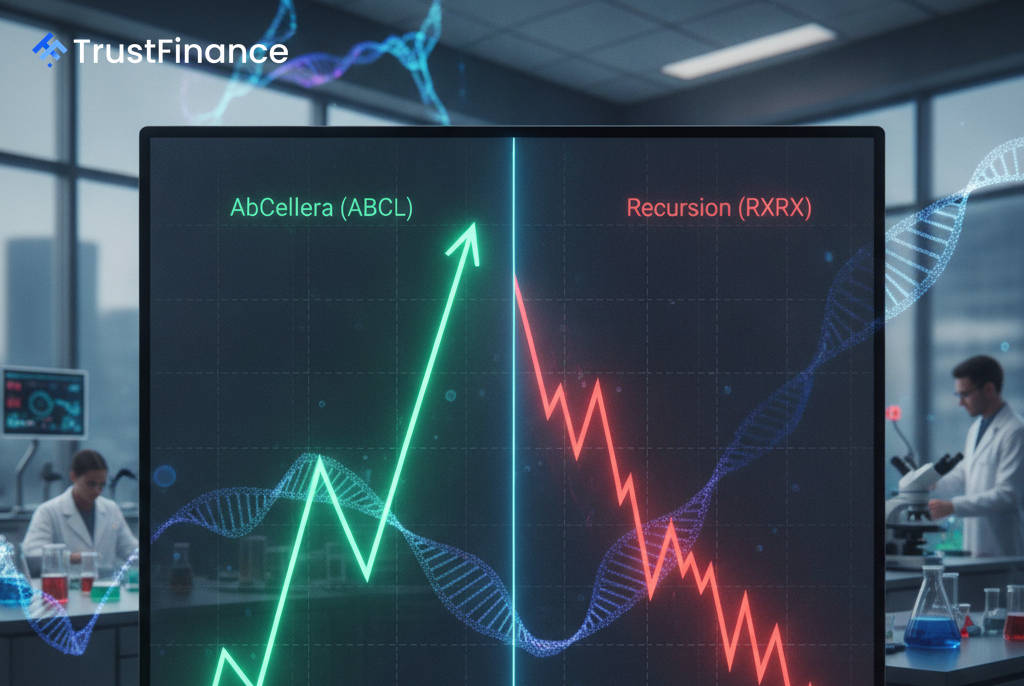
AI-driven drug discovery firms AbCellera and Recursion Pharmaceuticals show starkly different investment profiles. AbCellera's stock has surged but appears significantly overvalued ahead of a key clinical trial, while Recursion has slumped but trades closer to its fair value despite a high cash burn rate.
Shares of AI-driven biotechnology firms AbCellera (ABCL) and Recursion Pharmaceuticals (RXRX) are on sharply divergent paths, with valuation metrics and recent performance painting contrasting pictures for investors in the speculative drug discovery sector.
While both companies operate at the intersection of artificial intelligence and drug development, a closer look at their financials and market sentiment reveals two distinct risk-reward scenarios.
Valuation Gap Widens
The performance gap between the two clinical-stage biotechs has become significant over the past year. AbCellera's stock has delivered a +169.7% return, pushing its valuation to levels that appear stretched, while Recursion has seen its shares fall by -28.2%.
According to an analysis by Investing.com, this has created a stark valuation contrast:
- AbCellera (ABCL): Trading at $12.53, the stock is considered 44.4% overvalued compared to its fair value estimate of $6.96. It also trades at a higher price-to-book ratio of 4.5x.
- Recursion (RXRX): At a price of $3.66, the stock trades near its fair value estimate of $3.94. Analyst consensus targets suggest a potential upside of +97.7%, far exceeding the +17.8% upside projected for AbCellera.
Contrasting Fundamentals
 Ad
Neither company is currently profitable, which is common for firms in this stage, but their revenue and expense trends differ markedly. AbCellera's revenue has been volatile, collapsing from a high of $485 million in 2022, driven by COVID-era antibody royalties, to a projected $75.13 million in 2025. The company's gross margin remained deeply negative at -149% in 2025, indicating high costs relative to its revenue.
In contrast, Recursion has demonstrated steady top-line growth, with revenue increasing from $39.84 million in 2022 to a projected $74.68 million in 2025. However, a primary concern for Recursion is its accelerating cash burn. The company's EBITDA losses are forecast to widen to -$564 million in 2025 from -$326 million in 2023, highlighting a significant financial risk.
A Binary Bet vs. A Turnaround Play
The bull case for AbCellera hinges almost entirely on a single, high-stakes catalyst: the release of Phase 2 data for its drug candidate ABCL635, expected in the third quarter of 2026. This binary event could drive significant upside but also carries substantial risk. Technical indicators, such as a Relative Strength Index (RSI) of 71.95, suggest the stock is in overbought territory, reflecting the market's high expectations.
Recursion's investment case is more grounded in a potential valuation recovery. The market appears to have already priced in significant pessimism, and the stock is not showing the same signs of technical exhaustion. For investors, the key risk remains whether the company can manage its accelerating losses and sustain its operations until its drug pipeline can generate more substantial revenue.
Read next
More on Stocks
UBS Lifts AI Spending Forecast to $1.4 Trillion by 2027, Cites Soaring Memory Costs
UBS has dramatically raised its forecast for artificial intelligence capital expenditure, projecting it will reach nearly $1 trillion this year and $1.4 trillion in 2027, driven almost entirely by surging memory prices.
CFDA CEO Steven Kolb Resigns Following Physical Altercation with Protesters
Steven Kolb has stepped down as CEO of the Council of Fashion Designers of America after twenty years, following a widely publicized incident where he physically restrained animal rights activists at a New York Fashion Week show.

Anthropic Weighs New AI Model Release to Counter OpenAI Ahead of IPO, Sources Say
AI developer Anthropic is reportedly considering a new model launch to compete with OpenAI's recent success, a move that comes as the company prepares for an IPO and shortly after its CEO advocated for a slowdown in AI development.

Paramount, States Discuss CNN Oversight in Warner Bros. Merger Settlement Talks, Sources Say
Paramount and a dozen states are reportedly discussing a settlement to clear its $110 billion acquisition of Warner Bros. Discovery, with potential terms including independent monitoring of CNN and a commitment to theatrical film releases.