
Story
Palo Alto Networks Options Market Pricing In 8.6% Post-Earnings Swing
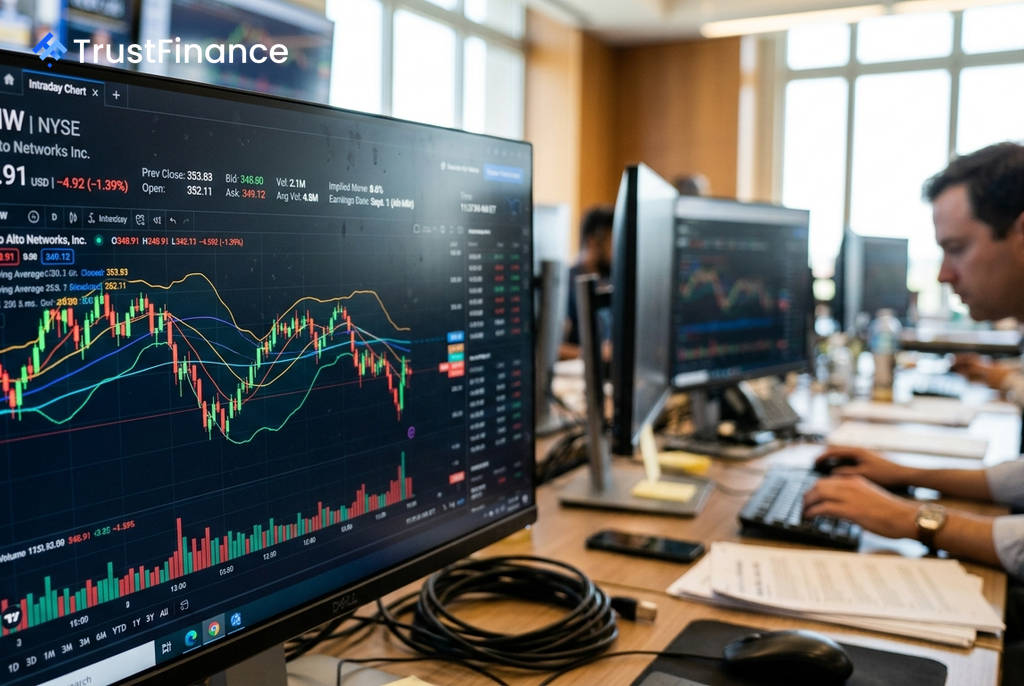
Options market data indicates a potential 8.6% swing in either direction for Palo Alto Networks (PANW) shares following the company's earnings report, scheduled for after the market close on September 1. This implied volatility, based on options pricing compiled by Bloomberg, reflects traders' expectations for the stock's reaction to the new financial results.
Historical Performance vs. Expectations
The cybersecurity firm's stock has a mixed record of meeting these market expectations. An analysis of the past eight earnings announcements shows that the stock's actual post-earnings move has exceeded the options-implied move in exactly half of those periods.
Key historical comparisons include:
- June 2: 8.0% implied move vs. 7.6% actual move
- February 17: 7.3% implied move vs. 8.2% actual decline
- November 2025: 7.3% implied move vs. 15.2% actual decline
- August 2025: 7.0% implied move vs. 8.7% actual rise
 Ad
What This Means for Investors
The implied move is a key metric derived from options prices that gauges the expected magnitude of a stock's price change, regardless of direction. It serves as a benchmark for market sentiment ahead of a significant catalyst like an earnings release.
The historical data for Palo Alto Networks illustrates that while the options market provides a useful gauge for potential volatility, the actual outcome can vary significantly. This highlights the inherent uncertainty and potential for surprise that surrounds corporate earnings reports.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.