
Story
IAG Named Top Airline Pick by Morgan Stanley Amid Normalizing Gulf Competition
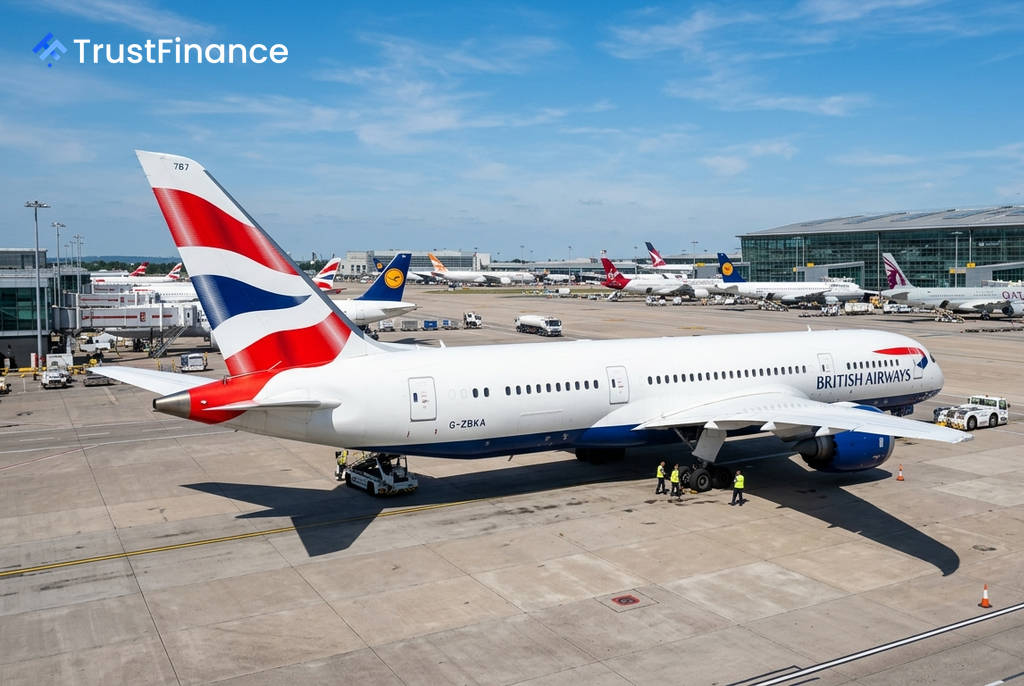
Morgan Stanley has upgraded International Airlines Group (IAG) to its sector "Top Pick," rating the stock as "Overweight" based on its resilient position as competition from Middle Eastern carriers returns. The bank argues that IAG's limited exposure to Asia provides significant insulation from the normalizing market conditions that benefited European airlines earlier this year.
Fading Tailwinds in Asia
A period of disruption for Gulf-based airlines created a significant windfall for European carriers in the second quarter of 2026, according to Morgan Stanley. This led to a supply-demand imbalance on Europe-Asia routes, allowing network carriers to command scarcity premiums and achieve double-digit yield gains.
However, the bank now sees this trend rapidly unwinding as capacity from Middle Eastern airlines rebounds. This normalization is expected to pressure the extraordinary pricing power European airlines have enjoyed, prompting analysts to become more selective about which carriers are best positioned to navigate the changing environment.
IAG's Defensive Positioning
Morgan Stanley's preference for IAG stems from its comparatively low reliance on the Asian market. The bank's analysis highlights a key difference in network structure:
 Ad
- IAG's capacity in the Asia-Pacific region is just 5%.
- In contrast, both Air France-KLM and Lufthansa have an exposure of roughly 15%.
This structural difference means IAG has far less earnings risk as Gulf carriers restore their flight schedules and competition intensifies. IAG management has echoed this sentiment, noting that while the benefits of diverted traffic will fade, the impact is "less material to group earnings" due to its smaller footprint in the region.
Market Outlook
Morgan Stanley believes the market has not fully appreciated IAG's relative earnings resilience. The bank notes that IAG's stock has seen a smaller re-rating compared to its peers, despite having the smallest cuts to its 2026 earnings per share (EPS) estimates, presenting a potential investment opportunity.
While IAG's lower exposure to Asia caps its potential upside if high fares persist longer than expected, its leading positions in other core markets, such as the North Atlantic, provide more durable pricing power. This positions the carrier with a more favorable risk-reward profile as the competitive landscape normalizes, according to the bank.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.