
Story
Douglas Shares Fall After Q3 Revenue and Profit Miss Expectations
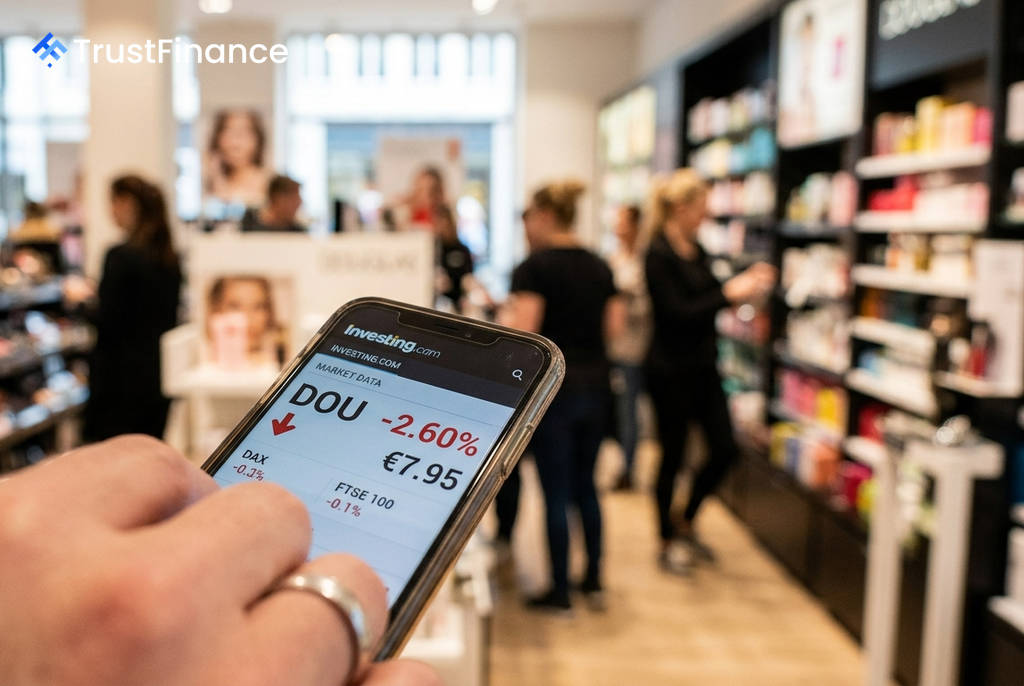
Shares in Douglas fell sharply on Wednesday after the German beauty retailer reported third-quarter financial results for its 2025/26 fiscal year that failed to meet analyst expectations for both revenue and profitability, culminating in a net loss for the period.
Disappointing Quarterly Performance
Douglas announced that its top-line and operating results deteriorated, highlighting weakening consumer demand. The company's performance missed Vara consensus estimates and showed a marked decline from the prior-year period.
- Net Sales: Declined approximately 2% year-over-year to €988 million, below the consensus forecast of €994 million.
- Like-for-Like Sales: Dropped by a more significant 4.5%, indicating pressure across its existing store network.
- Adjusted EBITDA: Fell nearly 19% to €127.5 million, missing the consensus of €131.5 million. This pushed the adjusted EBITDA margin down to 12.9% from 15.7% a year earlier.
- Net Income: The company posted a net loss of €2.6 million, a stark reversal from a net profit of €17.3 million in the same quarter last year.
Market Reaction and Outlook
The market reacted negatively to the earnings miss, with Douglas stock falling 2.6% to trade at €7.95, near its 52-week low of €7.60. The combination of lower sales, significant margin contraction, and the swing to a net loss weighed heavily on investor sentiment.
 Ad
Despite the poor quarterly results, Douglas management confirmed that its full-year guidance for the 2025/26 fiscal year remains unchanged. However, this reassurance was not enough to offset the concerns raised by the latest performance figures, suggesting investors are pricing in a challenging path to recovery.
Context and Analyst Concerns
The results land amid pre-existing concerns about the health of the German consumer. Analysts at Jefferies had previously trimmed their price target on the stock, citing worries about subdued spending on discretionary items like beauty products.
Wednesday's report underscores company-specific challenges, particularly a divergence between in-store and online performance, that go beyond broader market trends. The steep drop in like-for-like sales suggests fundamental operational headwinds for the retailer.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.