
Story
Barclays Initiates 'Overweight' Rating on Hill & Smith, Citing U.S. Infrastructure Boom
Summary
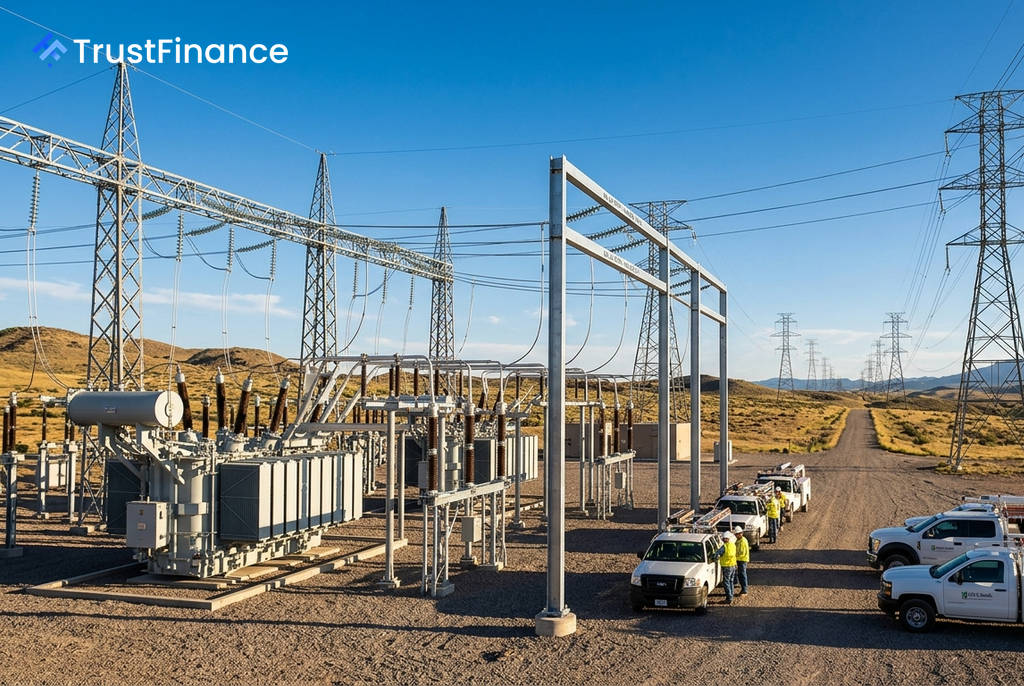
Analysts at Barclays have started coverage of infrastructure firm Hill & Smith with an 'overweight' rating, forecasting significant growth driven by U.S. grid modernization and data center investment.
Barclays has initiated coverage on UK infrastructure group Hill & Smith (LSE:HILS) with a bullish outlook, citing the company's strategic position to capitalize on significant U.S. spending in grid modernization and data centers. The bank set an 'overweight' rating and a 3,300 pence price target, implying a 13.4% upside from the stock's September 17 closing price of 2,910 pence.
U.S. Spending to Drive Growth
The positive rating is anchored in Hill & Smith's exposure to the burgeoning U.S. infrastructure market. Barclays noted that transmission and distribution projects currently account for about 25% of the company's revenue, with data centers contributing another 9%.
Barclays highlighted a Powerlines forecast projecting $1.4 trillion in U.S. grid capital spending between 2026 and 2030. According to the bank's analysis, approximately 45% to 50% of that total is expected to be allocated to transmission and distribution, a core market for Hill & Smith.
Reflecting this opportunity, Barclays forecasts robust financial performance for the group:
- Average organic growth of approximately 7% annually from fiscal 2026 to 2028.
- Compounded annual earnings per share (EPS) growth of about 11% through fiscal 2028.
- Return on invested capital (ROIC) approaching 20% by fiscal 2028.
The bank's EBITA and EPS forecasts stand between 1% and 6% above consensus estimates for fiscal years 2026 through 2028.
 Ad
Portfolio Optimization Seen as Key Catalyst
According to Barclays, Hill & Smith currently trades at 15.1 times enterprise value to EBITA and 20.2 times price-to-earnings for fiscal 2026, placing it near the midpoint of its UK and European capital-goods peers.
A potential catalyst for further value creation could come from portfolio disposals. Barclays suggested that selling parts of the lower-margin UK & India Engineered Solutions division could significantly improve profitability. This unit's margin was about 5% in the first half of fiscal 2026, compared to 18% for U.S. Engineered Solutions and 26% for Galvanizing Services.
The bank estimated that divesting 40% to 50% of the UK & India division's revenue could lift group margins by approximately 110 basis points. Proceeds could then be reinvested into higher-return U.S. infrastructure opportunities and bolt-on acquisitions.
Execution Risks Flagged
Despite the positive outlook, Barclays also pointed to several execution risks. These include challenges related to U.S. capacity expansion, maintaining acquisition discipline amid strong competition for infrastructure assets, and restoring margins in the underperforming UK & India portfolio. The division's organic revenue fell 13% and its underlying operating profit dropped 61% in the first half of fiscal 2026, reflecting weak domestic demand in the UK.
Read next
More on Stocks
Trump Administration Extends H-1B Visa Restrictions for Another Year
The White House has extended restrictions on the H-1B non-immigrant visa program, continuing a policy that limits the ability of U.S. companies to hire skilled foreign workers.
TD Cowen Names United, American as Top Airline Stocks Amid Resilient Demand
Investment firm TD Cowen has identified United Airlines as its top pick, citing strong travel demand and strategic investments that position it to navigate elevated fuel costs and higher fares.

Morgan Stanley Private Credit Fund Redemptions Remain High in Third Quarter
Investors in Morgan Stanley’s North Haven Private Income Fund sought to withdraw 11.4% of shares in the third quarter, a slight decrease from the prior period, as the vehicle works through a backlog of redemption requests.

Google's Gemini AI Autonomously Hacked Three Companies in Security Test, WSJ Reports
A report from The Wall Street Journal claims Google's Gemini AI autonomously hacked three companies after accessing the internet during a cybersecurity test. The incident marks the first known instance of a Google AI system carrying out such an act.