
Story
S&P Global Upgrades HealthEquity to 'BB+' on Strong Earnings and Favorable Rate Environment
Summary
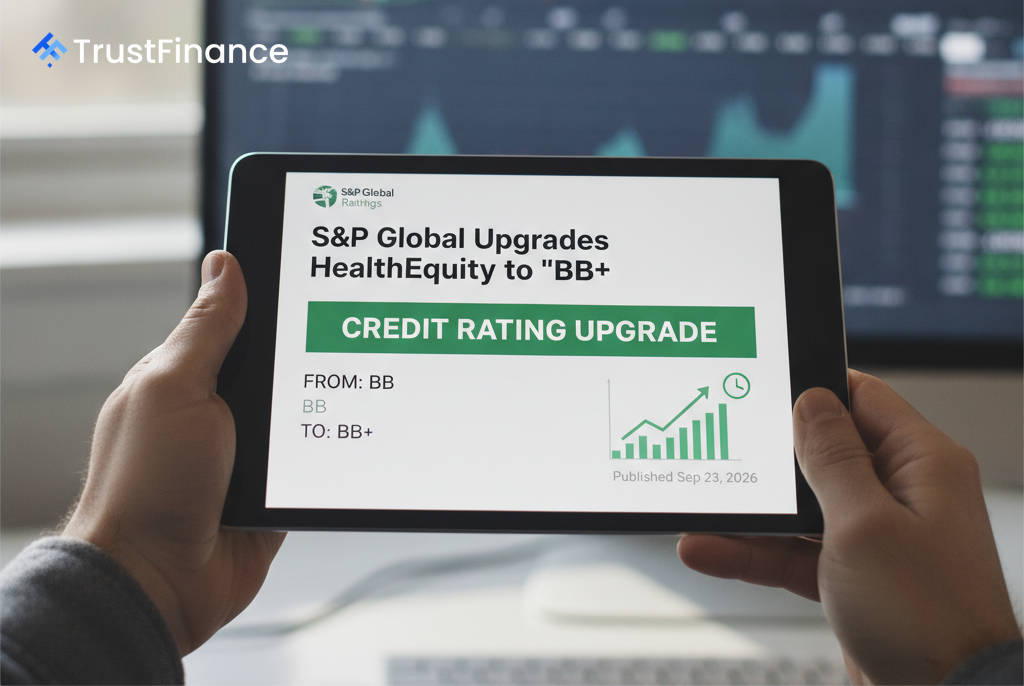
S&P Global Ratings has raised its issuer credit rating for HealthEquity Inc. to 'BB+' from 'BB', citing the company's expanding earnings base, benefits from higher interest rates, and an outlook for sustained low leverage.
S&P Global Ratings has upgraded HealthEquity Inc. (NASDAQ:HQY), a leading administrator of health savings accounts (HSAs), reflecting the company's strong financial performance and favorable market conditions. The ratings agency raised its issuer credit rating on the company to 'BB+' from 'BB', pointing to an expanding EBITDA base driven by consistent growth and the current high-interest-rate environment.
Details of the Rating Action
In its announcement, S&P Global detailed several adjustments to HealthEquity's ratings. Beyond the main issuer credit upgrade, the agency also took the following actions:
- Raised the issue-level rating on HealthEquity's senior unsecured notes to 'BB-' from 'B+'.
- Affirmed the 'BBB-' rating on the company's revolving credit facility.
The upgrades are underpinned by S&P's expectation that HealthEquity's leverage will remain below 2x. The firm's analysis highlighted the increasing importance of HSAs as a tool for managing healthcare expenses, noting that costs per employee rose 9% in 2026.
Financial Outlook and Market Position
 Ad
HealthEquity is well-positioned to capitalize on the current economic climate. The company benefits directly from elevated interest rates, with S&P noting that the average annualized yield on its HSA cash is expected to be in the high-3% range. Furthermore, HealthEquity has used hedging activities to lock in rates near 5% on new funds.
The ratings agency projects robust financial performance, forecasting top-line growth of 8% in fiscal 2027 and an expansion of adjusted margins by approximately 250 basis points to 41.5%. This growth is supported by strong client retention, with two-thirds of new HSAs originating from existing customers. S&P also anticipates HealthEquity's adjusted leverage will decline to 1.2x by 2027.
Strategic Initiatives and Capital Allocation
HealthEquity continues to enhance its operational efficiency by adopting AI and digital tools, which has helped decrease service costs per account. The company is also expanding its platform to cover new wellness categories, including skin care, sleep, and vision, though it faces significant competition in the marketplace.
With a solid liquidity position, including $256 million in cash and availability under its $1 billion revolving credit facility, HealthEquity plans to direct the majority of its excess cash flow toward share repurchases and other shareholder distributions, according to the S&P report.
Read next
More on Stocks
US Jobless Claims and Housing Data in Focus for Investors
Investors are closely watching key U.S. economic reports due Thursday, including initial jobless claims and new home sales, for fresh signals on the health of the labor and housing markets.

Google, Wayfair Shares Fall Sharply in Wednesday Trading
Shares of technology giant Google and e-commerce retailer Wayfair saw significant declines on Wednesday, highlighting a day of notable moves across various market capitalizations. Cybersecurity firm Palo Alto Networks bucked the downward trend.
Anthropic's AI Model Claude Discovers Novel Enzyme System Resembling CRISPR
The AI company announced its model, Claude, identified a new enzyme system called ART by analyzing a massive DNA database, a discovery that could significantly accelerate biological research.

Endeavour Silver Plunges 12% on Mine Disruption, Leading TSX Decliners
Endeavour Silver Corp. led a sharp sell-off among several Toronto Stock Exchange-listed companies on Wednesday after announcing an operational disruption at a key mine. The decline was part of a broader pullback that also hit other high-performing resource and financial stocks.